

Nothing to renovate
You move into a completed home that meets current standards, with no renovation budget to plan.
JL HOME compares new-build programmes for you across France and supports you at every stage: budget, choice of home, reservation, signing and delivery.
Who it's for
How it works
At each stage, you know what you need to do and what your JL HOME adviser takes care of.
Step 1 of 5
ReferenceThe overall budget includes the property price, notary fees and loan-related costs.
Step 2 of 5
Step 3 of 5
ReferenceA holding deposit is provided for under the reservation contract, and you then have a 10-day withdrawal period following its notification.
Step 4 of 5
ReferenceJL HOME is not a credit intermediary: your loan is negotiated between you and your bank or broker.
Step 5 of 5
ReferenceFor new-build homes, notary fees are reduced: around 2 to 3% of the price.
You move forward at your own pace, with a JL HOME adviser by your side until handover of the keys.
View homes to live inYou move into a completed home that meets current standards, with no renovation budget to plan.
The financial completion guarantee protects your purchase during construction; the guarantees of perfect completion, the two-year guarantee and the ten-year guarantee take over after delivery.
New homes follow the environmental regulations in force (RE2020 for recent building permits): enhanced insulation and reduced heating requirements.
JL HOME compares the developments of many developers and presents the homes that match your project, with clear information.
Depending on your situation and the home you choose, several schemes may reduce the cost of your purchase. Your adviser will check with you which ones apply.
An interest-free loan that part-finances your new main residence, if you have not owned your main residence in the last two years, subject to income ceilings.
Find out more : Zero-rate loan (PTZ)In some areas undergoing urban renewal or nearby, a new-build home bought to live in may benefit from a TVA of 5.5% instead of 20%, subject to income ceilings.
Find out more : Reduced TVA at 5.5%In new builds, notary fees represent around 2 to 3% of the price, compared with around 7.5 to 8.5% in existing properties.
Find out more : Reduced notary feesThe BRS lets you buy the home at a controlled price, while the land remains owned by an organisme foncier solidaire (OFS), subject to income ceilings.
Find out more : Bail réel solidaire (BRS)Depending on your project and situation, certain schemes may or may not apply. Your JL HOME adviser will go through this with you.
Choose your home
The search starts with a town and a budget, then narrows down to a specific home: its floor, its layout, its price.
Town or area, budget, number of rooms, outdoor space, delivery date: the search only keeps residences with at least one matching available home.
You set aside the developments you like and compare them side by side: price, floor area, floor, outdoor space, announced delivery.
Within each residence, available homes are listed one by one, with their type, floor area, floor and price. You choose yours.
The price is shown with its TVA regime. The plan opens on the listing when the developer has published it; otherwise your adviser requests it from the developer. Reduced notary fees for new-builds are added: around 2 to 3% of the price.
Website illustration. The developments and homes shown come from the current selection.
A few residences from the selection, each with a reference property. Ask your adviser for the plans of any that interest you.
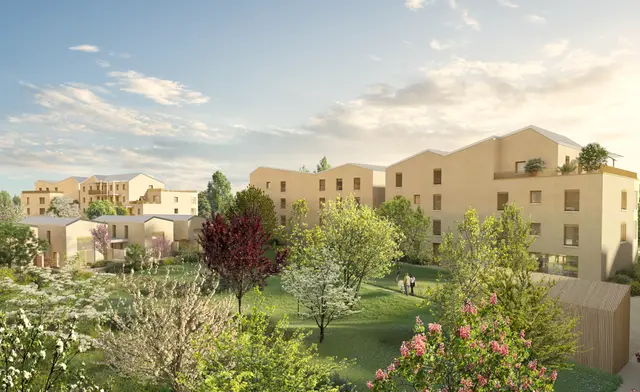 Residence image · non-contractual
PTZ possibly available for this property: main residence, subject to income conditions, first-time buyer status and bank approval.
Expected delivery Q4 2026
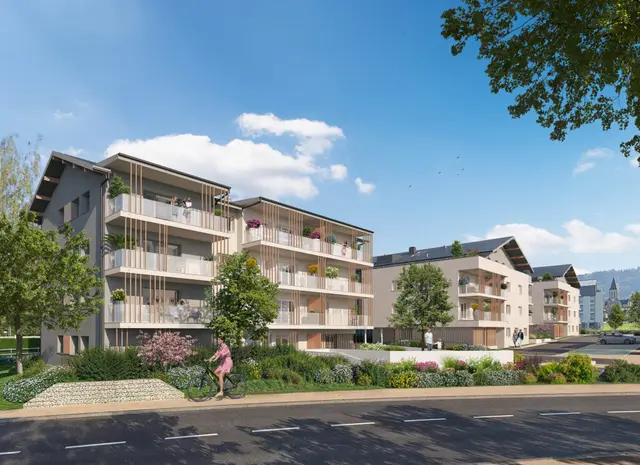 Residence image · non-contractual
PTZ possibly available for this property: main residence, subject to income conditions, first-time buyer status and bank approval.
Expected delivery Q1 2029
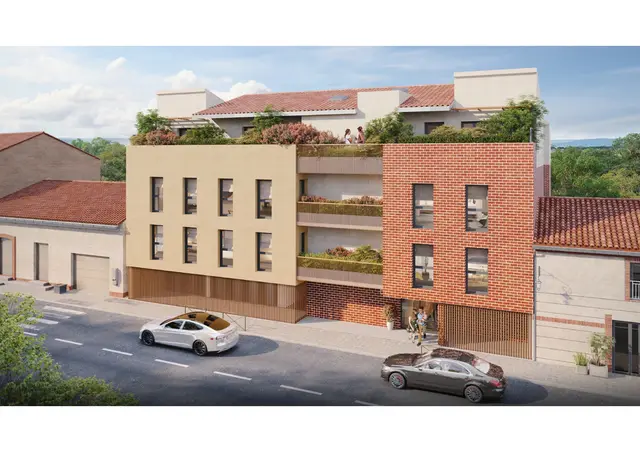 Residence image · non-contractual
PTZ possibly available for this property: main residence, subject to income conditions, first-time buyer status and bank approval.
Expected delivery Q4 2027
*Offer SM Promotion, subject to conditions and availability of the homes concerned.
Not always. Banks often ask for a deposit that covers at least the notary's fees and guarantee costs, but each application is assessed on a case-by-case basis. If you are entitled to it, the PTZ may supplement your financing. The level of deposit is to be discussed with your bank or broker.
Under a VEFA off-plan sale (vente en l’état futur d’achèvement), you pay the price in instalments as the works progress, according to a payment schedule set by law: no more than 35% on completion of the foundations, 70% when the building is watertight, 95% on completion, and the balance on handover of the keys.
During construction, the financial completion guarantee ensures the property will be finished. After delivery, the 1-year guarantee of perfect completion, the 2-year biennial guarantee and the 10-year decennial guarantee cover defects according to their nature.
No. JL HOME is not a credit intermediary: your loan is negotiated with your bank or your broker. Your adviser will send you the programme documents they need.
JL HOME is paid by the developer of the programme you buy: its fees are borne by the developer. Our work is to compare programmes, present homes suited to your project and support you until handover of the keys.
Yes. The selection covers new-build schemes in many towns across France, and your adviser will point you towards those that suit your project.
A JL HOME adviser will review with you your budget, the possible grants and the homes that suit you.
Speak to an adviser