Skip to content
Private landlord status · New build 2026

Jeanbrun scheme: depreciating a new rental investment

Le dispositif Jeanbrun (statut du bailleur privé) permet de déduire chaque année de vos revenus fonciers une part de la valeur d'un appartement neuf loué nu, sous plafonds de loyers et de ressources, pendant au moins 9 ans. JL HOME vérifie votre éligibilité avec vous.

  • Depreciation 3.5 to 5.5%/year
  • Apartment block, across France
  • Unfurnished letting, 9 years
  • Dedicated adviser

The JL HOME selection

Homes to consider for your project

Jeanbrun private landlord

Selection based on information from the developer. The scheme's conditions and the applicable price should be checked for your project.

One example property available per development. Open a listing to see the unit shown and its price conditions.

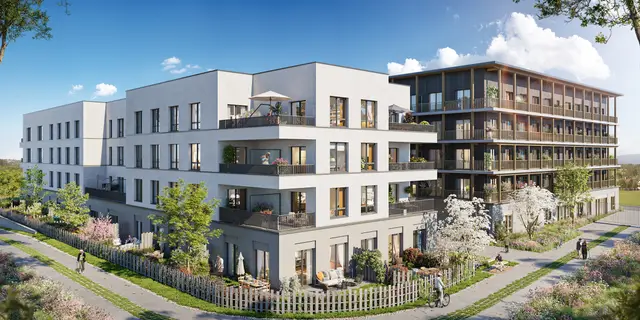
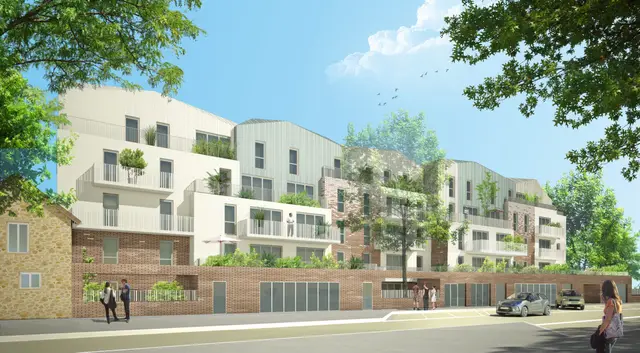
Les Jardins de Quentin, visuel 1Residence image · non-contractual
Ozoir-la-ferriere 77

Les Jardins de Quentin

€160,000Price provided by the developer · TVA to be confirmed

Price subject to access conditions, to be checked with your adviser.

PTZ possibly available for this property: main residence, subject to income conditions, first-time buyer status and bank approval.

Property ref. A001
1 main room (T1, French classification) · 29.94 m²
Floor
Ground floor

Expected delivery Q4 2026
In brief

The Jeanbrun scheme, in force since 21 February 2026, creates the private landlord status : by letting out an unfurnished new-build apartment to rent and income ceilings for for at least 9 years, you deduct each year from your rental income a depreciation calculated on 80 % of the price. It is a deduction, not a tax reduction: its effect depends on your tax position.

Why the Jeanbrun scheme

A depreciation scheme for new-build property

Depreciation

Depreciate the property's value

Each year, a portion of the property price (excluding land) is deducted from your property income. This is a deduction, not a tax reduction of the same amount: its effect depends on your tax situation.

Regulated letting

Rent and income ceilings

The property is let unfurnished, as a main residence, to tenants subject to income ceilings and capped rents, depending on the level chosen: intermediate, social or very social.

Across France

A new-build apartment in a block of flats

No zoning: the scheme applies throughout France, but only to homes located in a multi-unit residential building. Detached houses are excluded.

How it works

The 4 conditions of the Jeanbrun scheme

1

A new-build apartment in a block

A new or off-plan (VEFA) apartment in a multi-unit building, acquired between 21 February 2026 and 31 December 2028, anywhere in France.

2

Capped unfurnished rental

Let unfurnished as your main residence within 12 months of completion (or purchase, if later), at capped rents and incomes. The tenant may be neither a member of your tax household nor a relative or connection by marriage up to the 2nd degree.

3

9 years of letting

The letting must be actual and continuous for at least 9 years. This is a long-term commitment.

4

Deductible depreciation

3,5 % to 5,5 % a year of 80% of the price, deducted from rental income, up to 8 000 € a year per tax household (10 000 € or 12 000 € depending on the share of social or very social rental).

⚠️ The rental commitment is long for at least 9 years, and on resale the deducted depreciation reduces the acquisition price used for calculating any capital gain: a long-term asset investment to be considered within your strategy before you commit.

Depreciation

Jeanbrun depreciation levels

Depreciation applies to 80 % of the acquisition price: the land, estimated at a flat 20 %, cannot be depreciated. The lower the rents, the higher the annual rate. The deduction cap is assessed per year and per tax household: 8 000 €, raised to 10 000 € or 12 000 € if at least half of the gross rents come from social or very social lettings.

Rent levelDepreciable baseAnnual rateAnnual ceiling (per tax household)
Intermediary80 %3,5 %8 000 €
Social80 %4,5 %10 000 €
Very social80 %5,5 %12 000 €

Parameters of the 2026 Finance Act (CGI, art. 31). Rent ceilings: those of article 199 novovicies for the intermediate level, those of the Loc'Avantages scheme for the social and very social levels. Provided for information only: no gain is calculated or guaranteed.

Find out more

Combine the Jeanbrun scheme with the LLI

Via a SCI subject to income tax, the same new home can combine thedepreciation of the Jeanbrun scheme and the benefits of the LLI : VAT at 10% on purchase and a tax credit equal to the property tax for 20 years. The conditions of both schemes must be met at the same time: block of flats in a zone eligible for LLI, capped unfurnished letting and 20 years of rental under the LLI conditions (instead of 9 years for Jeanbrun alone). Eligibility and structuring depend on your situation. No yield or tax benefit is guaranteed or quantified here.

The JL HOME catalogue

Eligible Jeanbrun programmes

New-build programmes, some with apartments offered under the Jeanbrun scheme by their developer.

1 715eligible programmes
19 295eligible lots
78 497 €entry price
80 %depreciated base

JL HOME catalogue data (new programmes available). Observed median price: 284 400 €.

Why JL HOME

A demanding scheme, checked with you

The Jeanbrun scheme requires checking the building type, the rent level, the structure (direct ownership or an SCI subject to income tax), the 9-year commitment and the ceilings. A JL HOME adviser reviews this with you before any commitment, comparing programmes from several developers.

Frequently asked questions

Everything you need to know about the Jeanbrun scheme

What is the Jeanbrun scheme (private landlord status)?
Introduced by the Finance Act for 2026 and in force since 21 February 2026, the Jeanbrun scheme allows owners to deduct each year from their rental income a share of the value of a new unfurnished property let at capped rents and to capped incomes, for at least 9 years. It applies to acquisitions made up to 31 December 2028. A separate strand covers existing properties requiring works; this page covers new-build.
Does the Jeanbrun scheme replace the Pinel?
Pinel ended on 31 December 2024. The Jeanbrun scheme is a separate framework, in force since 21 February 2026, which works differently: Pinel gave a tax reduction calculated on the purchase price, whereas Jeanbrun provides a depreciation deduction against property income, with no zoning and only in multi-unit buildings.
What are the rent levels (intermediate, social, very social)?
Three tiers, with an annual depreciation rate of 3,5 % (intermediate), 4,5 % (social) or 5,5 % (very social) over 80 % of the price. The intermediate tier uses the rent and income ceilings of article 199 novovicies, the same as for LLI; the social and very social tiers use those of the Loc'Avantages scheme. The lower the rents, the higher the rate. The right tier depends on your strategy: an adviser will review this with you.
Can the Jeanbrun scheme be combined with the LLI?
Yes, subject to conditions. Held by an SCI subject to income tax, the same new-build home may benefit from the Jeanbrun depreciation and the advantages of the LLI: VAT at 10% and a tax credit equal to the property tax (taxe foncière) for 20 years. The conditions of both regimes must be met, including a zone eligible for the LLI and 20 years of letting under LLI conditions, instead of 9 years for Jeanbrun alone. Eligibility and structuring depend on your situation. No gain is guaranteed or quantified in advance.
What are the main conditions?
New-build or VEFA apartment in a multi-unit building, acquired between 21 February 2026 and 31 December 2028, anywhere in France; unfurnished letting as main residence within 12 months of completion (or of purchase, if later), for at least 9 years; rents and resources capped; tenant outside your tax household and not a parent or relative by marriage up to the 2nd degree; owner taxed under the real-expenses regime for property income, directly or via a company not subject to corporation tax (SCI subject to income tax, SCI à l'IR).
Does the Jeanbrun scheme guarantee a return?
No. No yield or tax benefit is guaranteed. Depreciation reduces your taxable property income depending on your situation, and on resale, the depreciation deducted reduces the acquisition price used to calculate the capital gain. A JL HOME adviser checks your case before any commitment, with no packaged product.

Your project

Check your Jeanbrun eligibility with an adviser

Your project begins here

What if this year were the right ?

Tell us what you are looking for. A JL HOME adviser will review your budget, then present the new-build developments that match your project, compared home by home.

Or call 06 38 76 14 85 or write on WhatsApp

  • Compared selectionThe homes that match your project, side by side.
  • Dedicated adviserA single point of contact from A to Z.
  • Multi-promoteursProgrammes from many developers, across France.
A JL HOME adviserAn adviserCallRequest a callback