Skip to content
LLI · New build 2026

LLI: investing in new-build in a high-demand area, with VAT at 10%

Intermediate rental housing (logement locatif intermédiaire) allows you to buy a new home subject to TVA at 10% and to offset the property tax (taxe foncière) through a tax credit, via a legal entity and in return for 20 years of rent-capped letting. JL HOME will check your eligibility with you.

  • TVA 10% (subject to conditions)
  • 20-year property tax credit
  • Mainly zones A bis · A · B1
  • Dedicated adviser

The JL HOME selection

Homes to consider for your project

LLI

Selection based on information from the developer. The scheme's conditions and the applicable price should be checked for your project.

One example property available per development. Open a listing to see the unit shown and its price conditions.

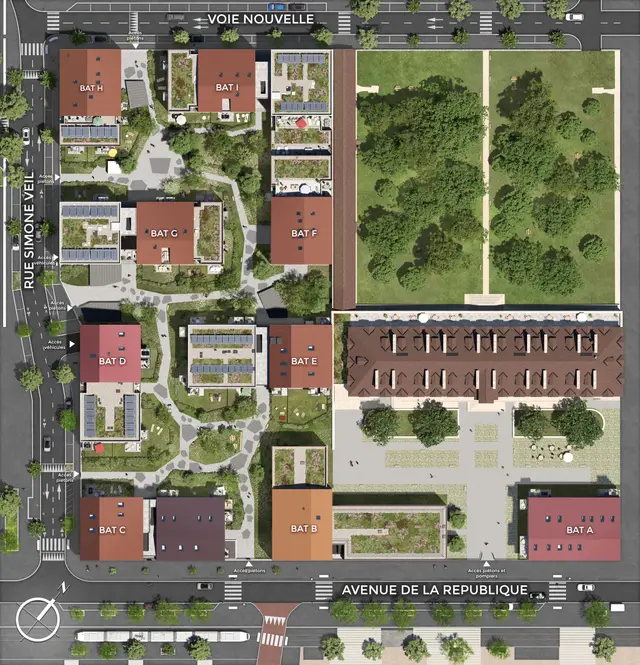
Evidence, visuel 1Residence image · non-contractual
Developer offer in progress*Offer Bouygues Immobilier
VILLENEUVE-LA-GARENNE 92390

Evidence

€176,917LLI VAT 10%

Price reserved for rental investment, subject to conditions.

Property ref. 01G-005
1 main room (T1, French classification) · 30.67 m²
Floor
Ground floor
Highlights
Aspect East
Floor plan preview for home 01G-005Layout previewRequest the full plan of this home.

Expected delivery Q1 2029

*Offer Bouygues Immobilier, subject to conditions and availability of the homes concerned.
In brief

The LLI (intermediate rental housing) is an investment framework in the new-build, mainly in zones A bis, A and B1. The buyer, who must be a legal entity (an SCI, for example) benefits from a 10% VAT (subject to conditions) and a tax credit equal to the property tax for 20 years, in exchange for 20 years of rental to rent and income ceilings.

Why LLI

A framework for investing in high-demand areas

Simplified acquisition

TVA at 10 %

The property is bought with TVA at 10% instead of 20%, subject to eligibility conditions. At an identical price excluding tax, the price including tax falls by about 8%, not 10%.

Rental security

A very broad rental target market

Intermediate rental housing targets households 'too well off for social housing, too modest for the open market', meaning a broad rental demand in tight-market areas.

Compensated property tax

A tax credit equal to the property tax (taxe foncière)

Property tax remains due, but a tax credit of the same amount is granted for 20 years (homes completed since 2023). This is not an exemption.

How it works

The 4 LLI conditions

1

A new-build property in an eligible area

A new-build or VEFA home, located mainly in zone A bis, A or B1, or in certain communes outside these zones. The programme must also meet a social-housing mix requirement, which the developer guarantees.

2

Via a legal entity

The 10% TVA rate is reserved for purchasers that are legal entities: an individual buys through a company, for example a family SCI. Buying in one's own name does not entitle you to it.

3

20 years of rental

The property must remain let under LLI conditions for 20 years. Otherwise, the additional TVA becomes payable; a resale avoids it only from the 11th year, subject to conditions.

4

Rent and income ceilings

Letting as a main residence, unfurnished or furnished, to households within income ceilings, with rents capped by zone and revised in line with the IRL.

⚠️ Letting under LLI conditions commits you for 20 years : it is a long-term wealth-building investment, to be factored into your strategy before you commit.

Zones & ceilings

2026 rent ceilings by zone

The LLI primarily targets zones A bis, A and B1; some municipalities outside these zones are also eligible. For an unfurnished letting, the rent is capped by zone, in euros per square metre per month (excluding charges), with a coefficient that depends on the surface area, then revised according to the IRL.

ZoneRent ceiling (€/m²/month)LLI eligible
A bis19,71 €Yes (tight-market zone)
A14,64 €Yes (tight-market zone)
B111,80 €Yes (tight-market zone)
B2 and C10,26 €Only certain communes

Ceilings for leases signed or renewed in 2026 (€/m²/month, excluding charges, before the surface coefficient), identical to those of the intermediate level of the Jeanbrun scheme. Source: BOFiP, BOI-BAREME-000017.

Benefits

The tax benefits of the LLI

10% VAT

Subject to conditions, the purchase bears VAT at 10% instead of 20%. At an identical price excluding VAT, this represents around 8% less on the price including VAT.

Property tax credit

A tax credit equal to the property tax, for 20 years. The tax is paid and then offset: this is not an exemption.

Property income

Held by an SCI subject to income tax (IR) and let unfurnished, the property falls under property income: deductible expenses and property deficit under standard rules. In an SCI subject to corporation tax (IS), rental income falls under corporation tax.

Rents indexed to IRL

Capped rents are revised in line with the rent reference index (IRL).

For property income, the property deficit can be offset against overall income up to 10 700 € per year (excluding loan interest, ordinary scheme), rising to €21,400 for certain energy renovation works paid up to 31 December 2027. Benefits are presented for information only, subject to eligibility conditions: no gain is quantified or guaranteed.

Find out more

LLI + Jeanbrun: combine both on the same property, subject to conditions

An individual accesses the LLI through a legal entity, for example a family SCI. If this SCI is to income tax, the same new-build home may also fall under the Jeanbrun scheme (private landlord status, in force since 21 February 2026), which allows an amortisation to be deducted from property income. The texts do not exclude this combination, but it requires complying with all the conditions of both schemes at the same time.

LLI · at purchase

10% VAT

TVA at 10% instead of 20% on acquisition, subject to eligibility conditions.

LLI · for 20 years

Property tax credit

A tax credit equal to the property tax (taxe foncière), over 20 years. This is not an exemption.

Jeanbrun · during the letting period

Deductible depreciation

Each year, 3,5 % of 80 % of the price at intermediate level, deductible from property income, up to a limit of 8 000 € per year and per tax household. This is a deduction, not a tax credit of the same amount.

Key conditions : SCI under IR (no purchase in your own name for LLI, no SCI under IS for Jeanbrun); home in a collective building (houses excluded from Jeanbrun), located in an area eligible for LLI; unfurnished letting as your main residence, with capped rents and income; tenant outside your tax household and not a parent or relative by marriage up to the 2nd degree; 20 years of letting under LLI conditions (Jeanbrun alone requires 9: LLI sets the horizon).

On resale, the depreciation deducted reduces the acquisition price used to calculate the capital gain.

This presentation is for information and educational purposes only. Eligibility, structuring and the combination of benefits depend on your circumstances and are subject to conditions. No return or tax saving is guaranteed or quantified here. A JL HOME adviser will check your situation before any commitment.

The JL HOME catalogue

Selected LLI programmes

The LLI is a selective scheme: fewer programmes than average, but targeted at high-demand areas.

593eligible programmes
7 800eligible lots
80 667 €entry price
3targeted zones

JL HOME catalogue data (new programmes available). Observed median price: 249 333 €.

Comparison

LLI, Jeanbrun, LMNP, BRS, PTZ: which framework?

Each scheme serves a different objective. A factual comparison: an adviser guides you according to your situation.

FrameworkLogicRentalCommitment
LLIVAT at 10% on purchase, plus a tax credit equal to the taxe foncièreBare or furnished, main residence, capped20 years of rental
JeanbrunDepreciation deducted from property incomeBare ownership, main residence, capped, apartment building9 years of letting
LMNPFurnished letting, reduced taxation of rental incomeFurnishedNo set duration
BRSSeparation of land ownership (reduced purchase price)Main residence (owner-occupier)Income conditions
PTZZero-rate loan (financing, not a rental scheme)Main residence (owner-occupier)Conditions d'occupation

Why JL HOME

A demanding scheme, checked with you

LLI requires checking the zone, the structure (SCI), the long-term commitment and the rent caps. A JL HOME adviser reviews this with you before any commitment, comparing developments from several developers.

Frequently asked questions

Everything you need to know about the LLI in new-build homes

What is LLI (intermediate rental housing)?
The LLI is a tax regime that encourages the production of intermediate-rent housing, mainly in zones A bis, A and B1. The purchaser, who must be a legal entity, benefits from a 10 % VAT rate and a tax credit equal to the property tax for 20 years. In return, the home must be let for 20 years to households below income ceilings, with capped rents.
Who can invest through an LLI and is an SCI needed?
A legal entity must be used: the TVA at 10% is reserved for buyers that are legal entities. An individual can therefore invest through a company, for example a family SCI, but not in their own name. The choice between an SCI subject to income tax (IR) and one subject to corporation tax (IS) changes the taxation of rents and determines whether it can be combined with the Jeanbrun scheme: a JL HOME adviser will go through this with you.
Which areas are eligible for the LLI?
Mainly zones A bis, A and B1, where rental demand is highest. Some municipalities outside these zones are also eligible, in particular those covered by a major nationally significant industrial project, a major urban development operation or a territorial revitalisation agreement. Eligibility is checked programme by programme.
What are the rent ceilings for LLI?
For leases concluded or renewed in 2026, the rent for an unfurnished LLI dwelling may not exceed, per month and excluding charges, 19.71 €/m² in zone A bis, 14.64 €/m² in zone A, 11.80 €/m² in zone B1 and 10.26 €/m² in zones B2 and C, with a coefficient that depends on floor area. For furnished rentals, ceilings set by decree apply. The ceilings are revised each year.
What is the commitment period for LLI?
The home must remain let under LLI conditions for 20 years. If letting under these conditions stops earlier, the additional TVA becomes payable. A resale does not trigger this additional payment from the 11th year, subject to conditions (before the 16th year, disposals cannot cover more than half of the homes). This is a long-term wealth-building investment.
LLI or LMNP: what’s the difference?
LMNP is the furnished letting regime, which reduces the taxation of rental income, with no commitment period imposed. The LLI provides VAT at 10% and a tax credit equal to the property tax, in exchange for 20 years of letting at capped rents and a purchase through a legal entity. The choice depends on your objective: an adviser will review it with you.
Can the LLI and the Jeanbrun scheme be combined?
Yes, subject to conditions. Held by an SCI subject to income tax, the same new home may benefit from 10% TVA and the LLI property tax credit (crédit d'impôt taxe foncière), and from the depreciation deduction under the Jeanbrun scheme (private landlord status, in force since 21 February 2026). All conditions of both regimes must be met: multi-unit building, LLI-eligible zone, unfurnished letting at capped rents and incomes, and 20 years of letting under LLI conditions. On resale, depreciation deducted is taken into account in calculating the capital gain. A JL HOME adviser checks your case before any commitment: no gain is guaranteed or quantified in advance.

Official sources

Sources accessed on · Page last updated on

Your project

Check your LLI eligibility with an adviser

Your project begins here

What if this year were the right ?

Tell us what you are looking for. A JL HOME adviser will review your budget, then present the new-build developments that match your project, compared home by home.

Or call 06 38 76 14 85 or write on WhatsApp

  • Compared selectionThe homes that match your project, side by side.
  • Dedicated adviserA single point of contact from A to Z.
  • Multi-promoteursProgrammes from many developers, across France.
A JL HOME adviserAn adviserCallRequest a callback